
Accessing Buy Now Pay Later through E-Wallets, Knowing Limits and Risks
Integrating Buy Now Pay Later (BNPL) services directly into e-wallets has transformed how consumers approach short-term financing for everyday purchases. These options offer unparalleled convenience, allowing users to defer payments or split costs into manageable installments right from their mobile devices. However, navigating these features effectively requires a clear understanding of the underlying requirements, the spending limits imposed, and the inherent risks involved.
Key Takeaways
- BNPL services in e-wallets provide convenient, short-term financing for purchases.
- Eligibility for these services is typically based on credit checks and specific e-wallet provider criteria.
- Understanding interest rates, potential fees, and the risk of accumulating debt is essential before use.
- Responsible BNPL engagement requires careful budgeting and a thorough review of all terms and conditions.
Initial Setup and Eligibility for E-Wallet BNPL
Before you can leverage the split-payment functionality within your preferred e-wallet, certain prerequisites must be met. Most e-wallet BNPL providers require users to be at least 18 years old, possess a valid government-issued ID, and have a verifiable bank account or debit card linked to their e-wallet. Residency in a supported country is also a standard requirement. The activation process often involves a soft credit check, which typically does not impact your credit score, to assess your repayment capacity.
Required Prerequisites & Tools:
- An active e-wallet account (e.g., Apple Pay, Google Pay, PayPal, specific regional e-wallets).
- A verified identity within the e-wallet platform.
- A linked and verified bank account or debit card for repayments.
- Stable internet connection for application and transaction processing.
- Sufficient credit history for the BNPL provider's assessment.
Activating and Utilizing Your Pay-Later Option
Integrating BNPL into your e-wallet streamlines the purchasing process significantly. The steps are generally intuitive, designed for quick adoption by tech-savvy consumers.
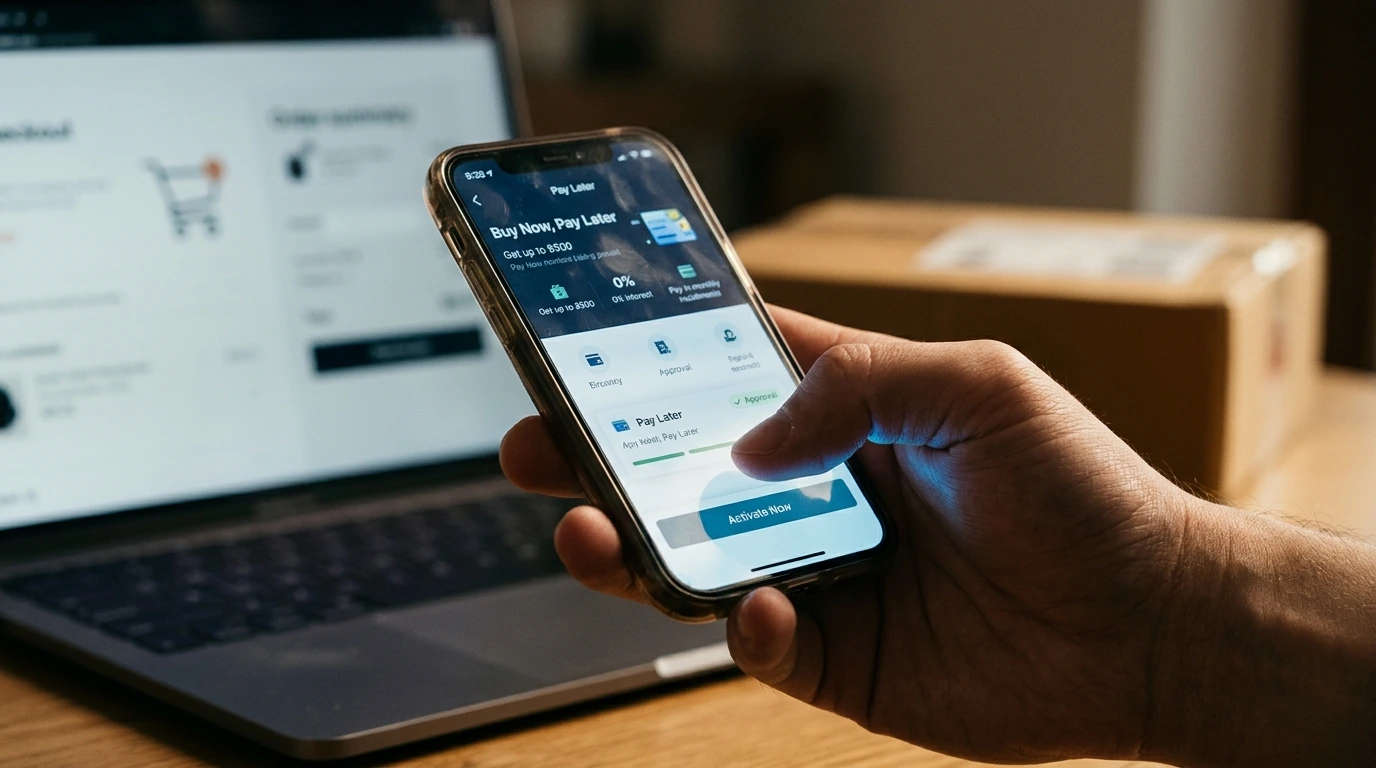
- Locate the BNPL Feature: Open your e-wallet app and navigate to the 'Finance', 'Payments', or 'Buy Now Pay Later' section. This is often prominently displayed or accessible through the main menu.
- Initiate Application: Follow the on-screen prompts to begin the application. This will typically involve confirming your identity, linking a repayment method, and agreeing to terms and conditions.
- Review Terms: Carefully read the interest rates (if any), repayment schedule, late fees, and any other charges associated with the service. This step is crucial for informed decision-making.
- Await Approval: Most applications are processed instantly. Upon approval, your available BNPL limit will be displayed within your e-wallet.
- Make a Purchase: When checking out online or in-store with your e-wallet, select the BNPL option at the payment stage. You will then choose your preferred installment plan.
- Confirm Transaction: Review the final payment breakdown and confirm the purchase. The first installment might be due immediately or on a specified future date, depending on the provider.
Navigating Common Challenges and Avoiding Costly Errors
While the convenience of BNPL is appealing, several pitfalls can lead to financial strain if not managed correctly. Understanding these can help users maintain financial health.
- Over-reliance and Debt Accumulation: The ease of splitting payments can lead to multiple simultaneous BNPL plans, making it difficult to track total obligations. This can quickly lead to unmanageable debt.
- Missing Repayment Deadlines: BNPL services often have strict repayment schedules. Missing a payment can result in significant late fees, which can quickly erode any perceived benefit of the service. Some providers may also report late payments to credit bureaus, potentially impacting your credit score.
- Ignoring Terms and Conditions: Failing to read the fine print can lead to surprises regarding interest charges, processing fees, or restrictions on returns and refunds when using BNPL.
- Impact on Credit Score: While initial soft checks are common, some BNPL providers may perform hard credit inquiries for larger limits or report payment behavior to credit bureaus. Consistent late payments can negatively affect your credit standing.
Pro Tip: Track All Repayments Diligently
Always use your e-wallet's built-in repayment tracker or set up external calendar reminders for all your BNPL installments. Automate payments where possible to avoid late fees, but ensure your linked account always has sufficient funds.
Confirming Your BNPL Transaction and Repayment Schedule
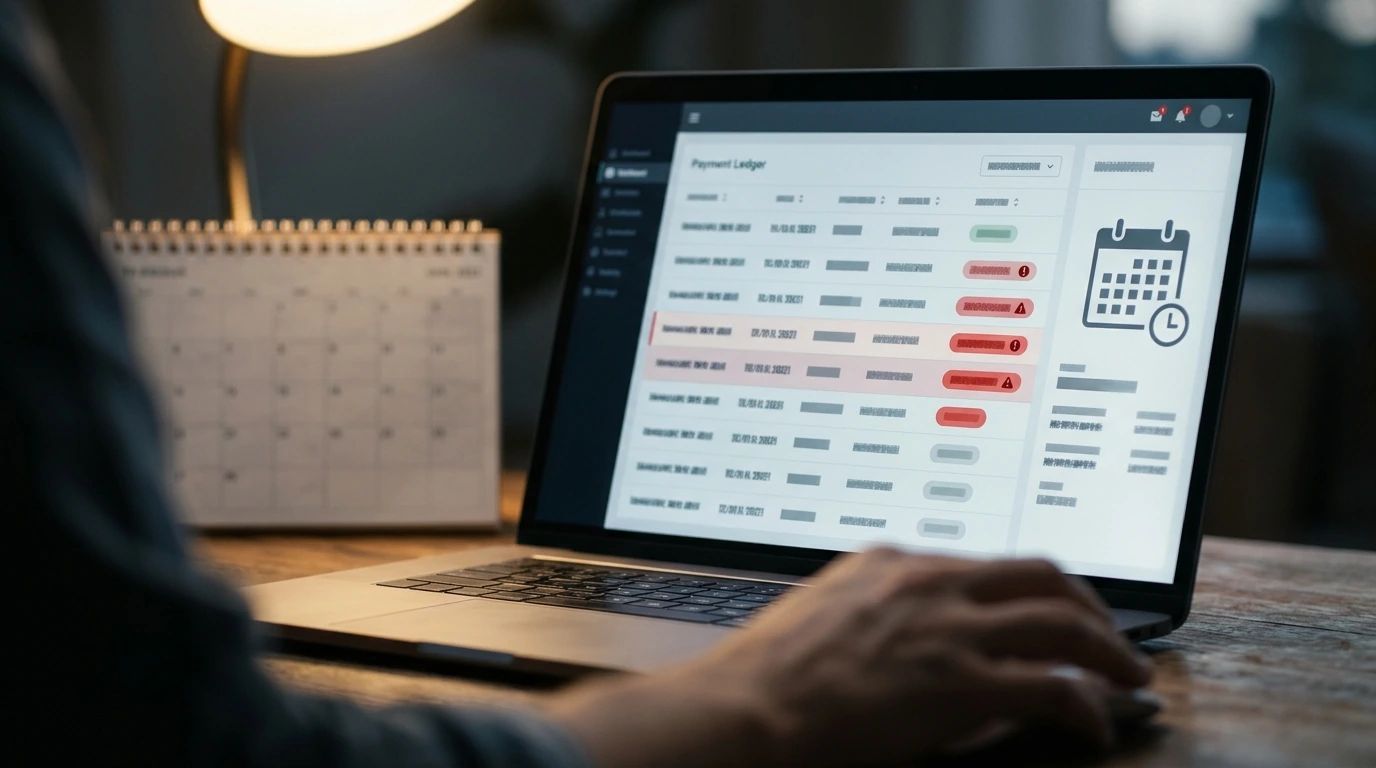
After completing a purchase with an e-wallet's BNPL option, verifying the transaction details and understanding the repayment structure is paramount. Most e-wallets provide a dedicated section to monitor your active BNPL plans.
Post-Implementation Verification Checklist:
- Immediate Confirmation: Check your e-wallet and email for a confirmation of your BNPL purchase, detailing the total amount, installment breakdown, and due dates.
- Repayment Schedule Review: Access the BNPL section in your e-wallet to verify the exact dates and amounts for each installment. Note any interest charges or fees applied.
- Linked Account Status: Ensure the bank account or debit card designated for repayments is correctly linked and has sufficient funds for upcoming installments.
- Alerts and Notifications: Confirm that e-wallet notifications for upcoming payments are enabled to receive timely reminders.
- Budget Integration: Incorporate BNPL repayments into your personal budget to ensure you can comfortably meet all obligations without financial strain.
Comparative Overview of E-Wallet BNPL Features
Different e-wallet providers may offer varying BNPL terms and conditions. The table below illustrates typical features reported across various platforms in 2026, though specific offerings can change.
| Feature | E-Wallet X Pay | E-Wallet Y Flex | E-Wallet Z Instalment |
|---|---|---|---|
| Eligibility Age (Minimum) | 18 years | 18 years | 21 years |
| Max Limit (Reported) | Up to $1,500 | Up to $2,500 | Up to $1,000 |
| Interest Rate (Typical) | 0% for 4 installments | 0-15% APR for longer terms | 0% for 3 installments |
| Late Fee (Typical) | $7-$10 per missed payment | Up to $25 or percentage of overdue amount | $5-$10 per missed payment |
| Credit Check Type | Soft inquiry | Soft/Hard (for higher limits) | Soft inquiry |
Demanding Workloads, Enduring Support: Evaluating 2026's Top Workstation Laptops for Data Science →
Frequently Asked Questions About E-Wallet BNPL
- What are the typical eligibility requirements for BNPL in e-wallets?
- Generally, you need to be 18 years or older, have a valid ID, a verified e-wallet account, and a linked bank account or debit card. A soft credit check is usually part of the application process.
- Can using BNPL affect my credit score?
- Initial applications often involve a soft credit check, which typically doesn't impact your score. However, some providers may perform hard inquiries for higher limits, and consistently missing payments can be reported to credit bureaus, potentially harming your credit score.
- What happens if I miss a BNPL payment?
- Missing a payment usually incurs late fees, as detailed in the service's terms and conditions. Repeated missed payments can lead to your account being suspended, collection efforts, and negative reporting to credit bureaus.
- Are there limits to how often I can use BNPL?
- While there isn't usually a strict limit on the number of active plans, providers assess your overall financial health and existing obligations. Your available spending limit will decrease with each active plan, and new requests may be declined if your current debt-to-income ratio is deemed too high.


Post a Comment for "Accessing Buy Now Pay Later through E-Wallets, Knowing Limits and Risks"